Short answer. We found no public per-lead mortgage price at the three vendors we checked, and the market for trigger leads was cut back by federal law on 4 March 2026. What can be read from primary sources today is this. Demand: Google Keyword Planner for the United States, read on 2 November 2026, puts "mortgage leads" and "mortgage lead generation" at 100 to 1,000 searches a month each, both down 90 percent year on year, "buy mortgage leads" at 100 to 1,000 and "refinance leads" at 10 to 100. Supply: the Homebuyers Privacy Protection Act, Public Law 119-36, now bars a credit bureau from selling a prescreened report triggered by a mortgage inquiry unless the buyer makes a firm offer of credit and has certified the consumer's authorisation to the bureau, originated or services the consumer's current mortgage, or is the consumer's own bank or credit union. Build cost: an AI speed-to-lead system on our mortgage lending page is from $2,497 one-time to build and from $1,997 a month to run, and our outbound B2B appointment packages run $2,997 to $9,997 and up a month. Compliance: $500 per violation under the TCPA for unconsented prerecorded calls, up to $500 for Do Not Call breaches, and state registrations from $50 to $1,500 where a lender or its vendor cold calls. The rest of this guide is the arithmetic for generating your own leads against those constraints.
Key numbers
| Item | Number |
|---|---|
| Homebuyers Privacy Protection Act approved (Public Law 119-36, H.R. 2808) | 5 September 2025 |
| Trigger-lead limits in effect since (180 days after enactment, section 3) | 4 March 2026 |
| US searches a month, mortgage leads (Keyword Planner; down 90% year on year, cause not given) | 100 to 1K |
| US searches a month, refinance leads (Keyword Planner, Low competition) | 10 to 100 |
| TCPA statutory damages (227(b)(3); up to $500 under 227(c)(5); treble if willful or knowing) | $500 per violation |
| Federal calling window (47 CFR 64.1200(c)(1)) | 8 a.m. to 9 p.m. |
| State telemarketer registration fees in our hub (security $10,000 to $100,000; lender exemptions vary) | $50 to $1,500 |
| AI speed-to-lead build (live in 2 to 4 weeks) | $2,497 one-time, from |
| AI speed-to-lead managed (year one from $26,461 with the build, before vendor usage) | $1,997 a month, from |
| Outbound B2B appointment packages (20 to 150 or more B2B sales appointments) | $2,997 to $9,997 and up a month |
congress.gov (H.R. 2808 text and status), Google Keyword Planner (United States), eCFR 47 CFR 64.1200, state statutes in our registration hub and the imisofts mortgage lending and lead generation pages, read on 2 November 2026.
Why we quote no price per lead
We looked for a mortgage lead vendor with a public per-lead price on 2 November 2026 and did not find one we could cite: the consumer-insurance vendor whose public prices we use elsewhere lists no mortgage vertical, the mortgage lead-generation platform we checked routes its pricing page to a custom-quote form, and a third vendor's page did not load. At those three, mortgage lead prices were not published. So this guide does not pretend to a market average. It prices the inputs you control: the demand you can capture, the law you must satisfy, and the system that answers the lead.
What the demand signal says
Keyword Planner's United States view (location set to the United States, English, Google, October 2025 to September 2026) gave these ranges for the seed terms:
| Keyword | Average monthly searches | Year-on-year change | Competition |
|---|---|---|---|
| mortgage leads | 100 to 1K | -90% | Medium |
| mortgage lead generation | 100 to 1K | -90% | Medium |
| buy mortgage leads | 100 to 1K | 0% | Low |
| refinance leads | 10 to 100 | 0% | Low |
Two readings. Two of the four seed terms fell 90 percent year on year, as did two insurance-lead terms in the same pass; Keyword Planner gives no cause. And the volumes are small; this is a market of lenders and brokers, not consumers, so the consumer-side keywords (rates, refinance, first-time buyer) are where paid acquisition actually happens. Our account's bid columns display in Pakistani rupees, so we do not quote cost-per-click figures here; the search ranges and competition labels are currency-free and are the figures we rely on.
The trigger-lead change, in the statute's words
H.R. 2808, the Homebuyers Privacy Protection Act, was approved on 5 September 2025 and, per its section 3, took effect 180 days later, on 4 March 2026. Section 2 adds to the Fair Credit Reporting Act's prescreening rules: "If a person requests a consumer report from a consumer reporting agency in connection with a credit transaction involving a residential mortgage loan, that agency may not, based in whole or in part on that request, furnish a consumer report to another person under this subsection unless" the transaction "consists of a firm offer of credit or insurance" and the other person either has submitted documentation certifying the consumer's authorisation, "has originated a current residential mortgage loan of the consumer," "is the servicer of a current residential mortgage loan of the consumer," or is an insured depository institution or credit union that "holds a current account for the consumer." The Act also orders a GAO study of trigger leads received by text message within 12 months of enactment. Who can still buy trigger leads, and what the certification route involves, is covered in are mortgage trigger leads illegal; the point for cost is that a high-intent list now has a legal gate, and inside the gate are certified-authorisation buyers and the consumer's current originator, servicer, bank or credit union.
What compliance adds to every lead you work
- Federal calling rules. The TCPA allows $500 per violation under 227(b)(3) for calls such as unconsented prerecorded calls, and up to $500 under 227(c)(5) for Do Not Call breaches after more than one call in 12 months, with up to treble damages if willful or knowing, and 47 CFR 64.1200(c)(1) bars telephone solicitations to residential numbers before 8 a.m. or after 9 p.m. at the called party's location. A hundred unlawful calls is $50,000 at the base figure and up to $150,000 at the top. Our mortgage page says the FCC's one-to-one consent rule was vacated; the rules that remain are in TCPA opt-out requirements and TCPA vicarious liability.
- State registration, with the lender exemptions. Where a lender or its vendor cold calls into a registration state, the fees in our registration-by-state hub run $50 to $1,500 with security of $10,000 to $100,000. Some states exempt some lenders: Texas Business and Commerce Code 302.053 excludes supervised financial institutions and their affiliates, Washington's RCW 19.158.020 excludes supervised financial institutions from its solicitor definition, Pennsylvania's section 3(b.1)(5) exempts businesses licensed or registered with a federal or state agency acting within that scope, and California's 17511.1(e)(21) exempts licensed residential mortgage lenders. A non-bank marketing vendor calling on a lender's behalf may not share those exemptions, which is a question to settle before the vendor dials. State windows can be narrower even where registration is exempt; Pennsylvania's is 9 a.m. to 7 p.m., no Sundays or legal holidays.
- Licensing on the call itself. Whether an AI agent may discuss rates or terms is a licensing question, covered in your AI voice agent can call your mortgage leads, it cannot quote them.
What it costs to generate and answer your own leads
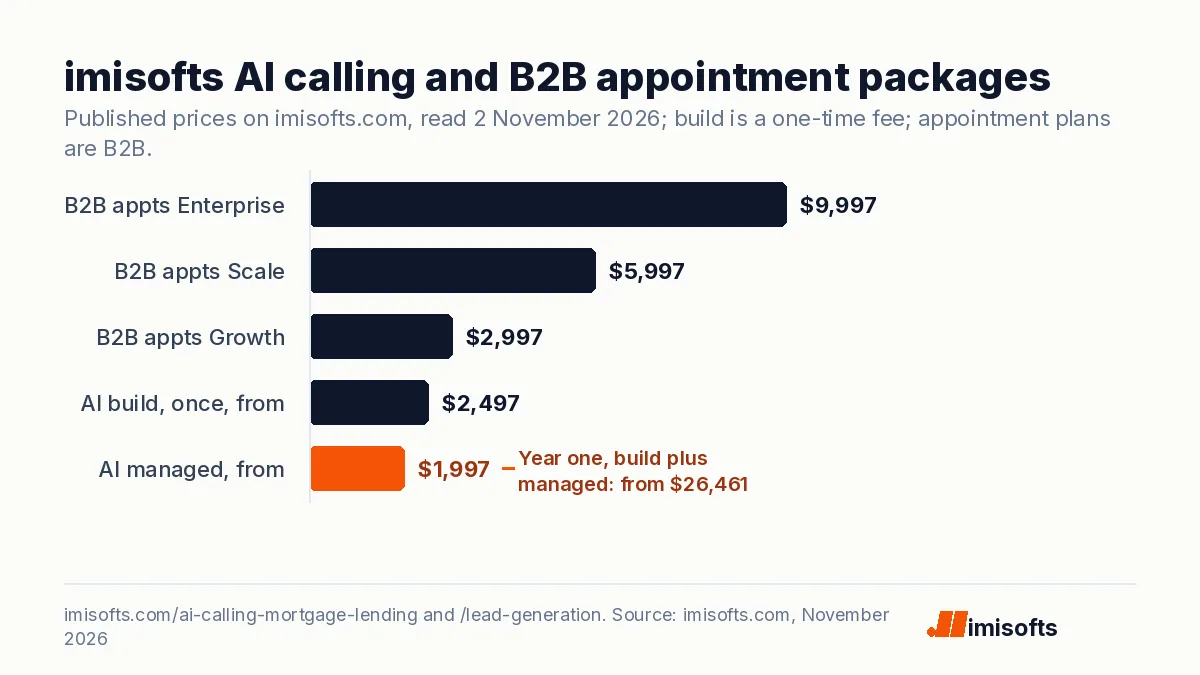
With bought lists constrained, the alternative is to generate inbound leads and answer them fast. Our published prices for that stack:
| Component | Price | What it is |
|---|---|---|
| AI speed-to-lead system, build | $2,497 one-time, from | Call flows, scripts, integration, recording and handoff rules, live in 2 to 4 weeks |
| AI speed-to-lead system, managed | $1,997 a month, from | We run it and tune it; telephony, voice engine, list screening and CRM billed by those vendors |
| Outbound B2B appointments, Growth | $2,997 a month | 20 to 40 qualified B2B sales appointments with a dedicated SDR |
| Outbound B2B appointments, Scale | $5,997 a month | 40 to 80 qualified B2B sales appointments |
| Outbound B2B appointments, Enterprise | $9,997 and up a month | 80 to 150 or more qualified B2B sales appointments |
Year one, if the build fee also applies to Managed, is $2,497 plus twelve months at $1,997, or from $26,461, before vendor usage bills. On the appointment packages the implied cost per qualified appointment is $74.93 to $149.85 on Growth and $66.65 to $124.96 on Enterprise at $9,997. Those are B2B sales appointments, not borrower inquiries, so they are not comparable to a trigger lead's price even where one is quoted; our pricing page also lists an outbound demo-booking plan at $2,497 a month on Growth and from $4,997 on Scale.
Why speed is the cost lever in mortgage
Until March 2026 a mortgage inquiry itself generated competing calls through trigger leads. With that channel narrowed, the lender that answers its own inbound inquiry first has fewer competitors on the line, and the cost of a lead is set by how many of them you reach while they are still shopping. The research on response time and contact rates is summarised in speed to lead; the system cost above is what it takes to respond around the clock, with the consent and hours rules built into the call flows. Platforms that can do that are compared in the best AI voice agents in 2026.
A cost model you can fill in
- Monthly marketing spend on consumer-side keywords and channels, divided by inquiries received, gives cost per inquiry. We do not quote a market CPC here; take yours from your own ads account in your own currency.
- Inquiries contacted within the first minutes, divided by inquiries received, is the contact rate the system cost above is buying.
- Applications divided by contacted inquiries gives the conversion the loan officers control.
- Add the fixed compliance layer: registrations where you are not exempt, the consent records, and the monitoring that reduces the per-violation exposure.
- Compare the result with any vendor quote per lead, remembering that a bought lead still has to be contacted and consented, and that who may quote it is a licensing question.
Every figure above is from a primary page read on 2 November 2026: congress.gov for the Act, Keyword Planner for demand, eCFR for the federal window, state statutes for registration, and our own pages for prices. The one number we could not publish, a price per mortgage lead, is the one to ask each vendor for in writing, with the state, loan type and exclusivity attached. This is general information, not legal advice.
Frequently Asked Questions
We found no public per-lead mortgage price at the three vendors we checked on 2 November 2026. What is published is the cost of generating and answering your own: our AI speed-to-lead system is from $2,497 to build and from $1,997 a month to run, and our outbound B2B appointment packages are $2,997 to $9,997 and up a month.
Only within the Homebuyers Privacy Protection Act, Public Law 119-36, in effect since 4 March 2026. A credit bureau may furnish a prescreened report triggered by a mortgage inquiry only for a firm offer of credit or insurance, and only to a buyer that has certified the consumer's authorisation to the bureau, originated or services the consumer's current mortgage, or is a bank or credit union holding the consumer's current account.
Google Keyword Planner for the United States, read on 2 November 2026, shows 100 to 1,000 monthly searches each for mortgage leads, mortgage lead generation and buy mortgage leads, with the first two down 90 percent year on year, and 10 to 100 for refinance leads.
It depends on the state and the caller. Texas excludes supervised financial institutions and their affiliates, Washington excludes supervised financial institutions from its solicitor definition, Pennsylvania exempts businesses licensed or registered with a federal or state agency acting within that scope, and California exempts licensed residential mortgage lenders. A non-bank marketing vendor calling on a lender's behalf may not share those exemptions.
On our mortgage lending page, the build is from $2,497 one-time and the managed service from $1,997 a month, live in 2 to 4 weeks, with telephony, voice engine, list screening and CRM usage billed by those vendors. Year one is from $26,461 before those usage bills, if the build fee also applies to Managed.
$500 per violation under 227(b)(3) for calls such as unconsented prerecorded calls, and up to $500 under 227(c)(5) for Do Not Call breaches after more than one call in 12 months, which a court may raise up to threefold for willful or knowing violations; a hundred (b)(3) violations is $50,000 to $150,000. Telephone solicitations to residential numbers are also barred before 8 a.m. or after 9 p.m. at the called party's location under 47 CFR 64.1200(c)(1).