November 4, 2026. From November 20, 2026, 16 days from now, EU countries must apply their national laws implementing the new Consumer Credit Directive, Directive (EU) 2023/2225, which replaces the 2008 directive and covers small loans under €200 and, on our reading, buy now, pay later schemes run by a third party. A shop that lets customers pay later on its own terms stays outside it only if no third party offers the credit, the price is free of interest and other charges apart from limited late fees, and it is paid in full within 50 days of delivery, or within 14 days for online sellers that are not SMEs.
Key numbers
| Item | Number |
|---|---|
| New rules apply from (16 days after this article) | November 20, 2026 |
| Deadline to adopt national laws | November 20, 2025 |
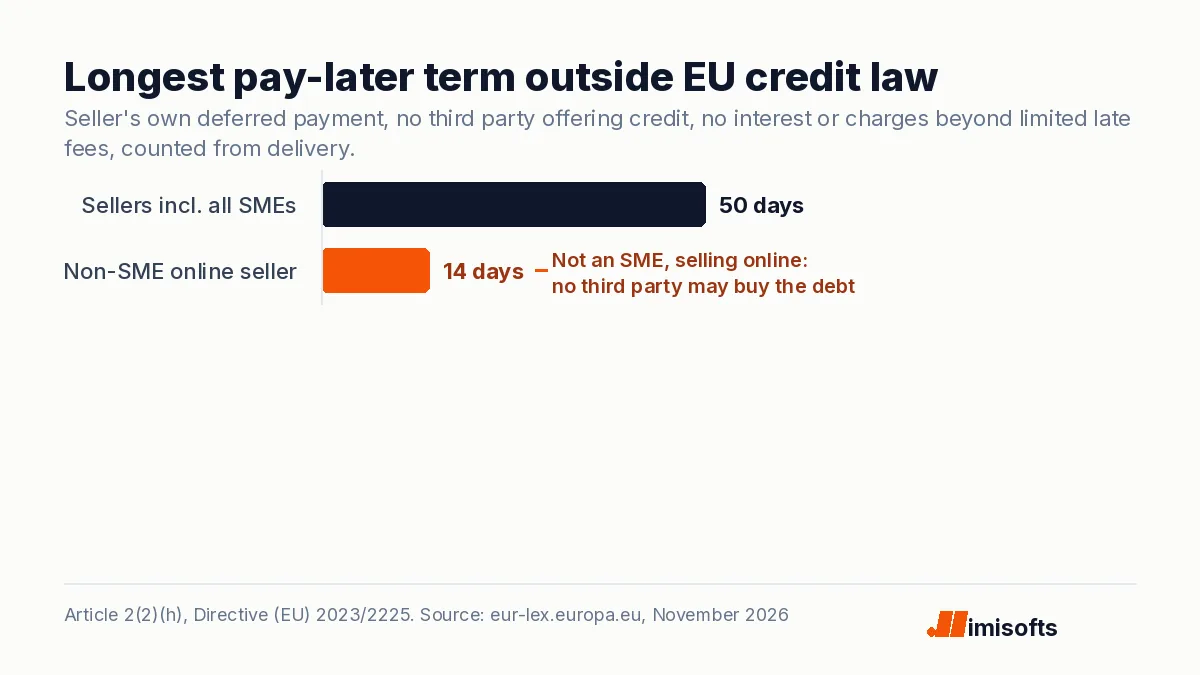
| Seller's own pay-later term outside the rules (from delivery; no interest or charges beyond limited late fees; no third party offering credit) | Up to 50 days |
| Same term for non-SMEs selling online (and no third party may buy the debt) | Up to 14 days |
| Old floor for consumer credit rules (credit below it is now covered) | €200 |
| Upper limit of the directive | €100,000 |
Directive (EU) 2023/2225 text on EUR-Lex, read on 4 November 2026.
What the directive changes for online sellers
- The dates. Article 48 told Member States to adopt and publish their national laws "by 20 November 2025" and to "apply those measures from 20 November 2026." Article 47 repeals the 2008 directive from the same day, but it "shall continue to apply to credit agreements existing on 20 November 2026 until their termination."
- Small and interest-free credit is now in scope. A recital says credit under €200, credit "granted free of interest and without any other charges" and credit repaid within three months with only insignificant charges, all excluded under the 2008 directive, should now be covered. Credit above €100,000 stays outside.
- The merchant exclusion is narrow. Article 2(2)(h) excludes deferred payment where the seller gives the consumer time to pay "without a third party offering credit", free of interest and charges apart from limited late fees, and paid in full "within 50 days of the delivery of the good or service." Recital 17 names "'buy now, pay later' schemes" as the kind of third party that keeps a sale out of the exclusion.
- Large online sellers get 14 days. For sellers that are not micro, small or medium-sized enterprises under Recommendation 2003/361/EC and that sell to consumers at a distance online, the exclusion applies only if "a third party is neither offering nor purchasing credit", the price is free of interest and other charges apart from limited late fees, and payment is made in full "within 14 days of the delivery".
- Checkout and adverts change. Article 8(1) requires credit advertising to carry the warning "Caution! Borrowing money costs money" or equivalent wording, and Article 15 bars creditors and credit intermediaries from inferring consent through default options: "Default options include pre-ticked boxes."
What it means for operators
On our reading, a store that only takes standard card payments without instalments, direct PayPal payments or bank transfers is not offering credit. Unzer's merchant FAQ says such merchants are "generally not affected" and that, in principle, "the old de minimis threshold of €200 no longer applies"; Unzer sells its own pay-later product, so it has a stake. If you sell to EU consumers, we would check four things before November 20:
- Your own pay-by-invoice terms. On our reading, they stay outside the directive only if no third party offers the credit (for a non-SME selling online, none may buy the debt either), there is no interest and no charge beyond limited late fees, and payment is made in full within 50 days of delivery, or 14 days for a non-SME selling online.
- Your BNPL app. On our reading, the BNPL provider is usually the creditor. Article 11(8) spares sellers acting as credit intermediaries "in an ancillary capacity" from the pre-contract information article but keeps the creditor's duty to deliver that information, so ask your provider which plugin or app update it ships for November 20.
- Pre-selected payment options. We would not pre-select a pay-later option at checkout.
- Ads that mention 0% or "pay in 3". Check the warning wording your country's law requires, since national law may use the directive's wording or an equivalent.
The final rules sit in your country's implementing act. If your checkout needs changes, our Shopify developers handle app integration, payment gateway setup and checkout work as part of our e-commerce services, and our Shopify app reviews compare the apps involved. For another EU rule that changed this month for sellers outside the EU, see EU product identifiers. This is general information, not legal advice.
Frequently Asked Questions
From November 20, 2026. Directive (EU) 2023/2225 told Member States to adopt their national laws by November 20, 2025 and apply them from November 20, 2026, when the 2008 directive is repealed. Credit agreements that exist on November 20, 2026 stay under the old rules until they end.
On our reading, yes where a third party offers the credit. The directive's deferred-payment exclusion covers only payment terms the seller gives itself, with no third party offering credit, free of interest and charges apart from limited late fees, and paid in full within 50 days of delivery (14 days for non-SMEs selling online). Recital 17 names buy now, pay later schemes as the third-party case.
Yes. A recital says credit under €200, excluded from the 2008 directive, should be covered by the new one, though Article 2(8) lets each Member State switch off a few provisions for agreements under €200, interest-free credit and credit repaid within three months with insignificant charges.
On our reading, yes, if the shop gives the time to pay itself with no third party offering credit, charges no interest or fees beyond limited late charges, and the payment is made in full within 50 days of delivery. For online sellers that are not SMEs, the limit is 14 days and no third party may buy the debt either.